

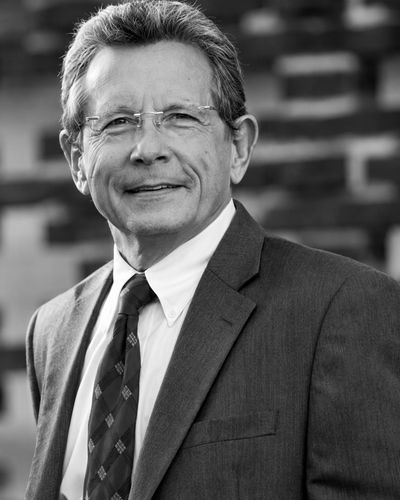
In plain terms — Larry Williams is an American trader and author known for turning several market observations into measurable rules. His name is chiefly associated with Williams %R, COT data, and the study of seasonality.
Who he is, briefly
Williams began following markets in the 1960s and went on to work across futures trading, research, books, and education. His biographical site dates the development of Williams %R to 1966; Wiley catalogues document books covering short-term trading, volatility, money management, and the use of the Commitments of Traders report.
The World Cup Trading Championships historical standings list Williams as the 1987 winner with an 11,376% net return. That figure is published by the contest organizer. Cyclepedia does not have the complete trade series, withdrawals, drawdown, or an independent verification from which to reconstruct the risk taken. It is therefore presented as an organizer-reported result, not an expected return or proof that the techniques are replicable.
Master path
Study Larry Williams in a clear order
Begin with the essential idea, move to the procedure, and finish with what can invalidate the reading.
- Start here Williams %R: the close's position within the range Williams %R places the close between the highest high and lowest low of a recent window: zero is the upper edge and -100 the lower; extremes need context.
- Understand the model COT report Commitment of Traders — weekly institutional and spec positioning on CFTC futures; macro context.
- Learn the procedure Market seasonality Recurring calendar patterns — months, weekdays, session turns; contextual filter, not a deterministic rule.
- Learn the procedure Position sizing A method for converting a risk budget and stop distance into tradable quantity, including point value, costs, rounding and portfolio constraints.
- Testing and limits Backtest Historical simulation of a strategy using point-in-time data, causal rules, realistic execution, and bias controls before any inference is made.
The documented contribution
Williams %R: where price closes
Williams %R measures the close relative to the highest high and lowest low of a recent window. A close near the high moves the value toward zero; a close near the low moves it toward −100. It is a position measure related to the Stochastic, not an automatic order. An extreme reading can persist with a trend rather than immediately predict a reversal.
COT and seasonality: context beyond the chart
Williams helped popularize operational uses of the Commitments of Traders report. The CFTC groups reported positions each week according to regulatory categories. “Commercial” does not automatically mean informed and “non-commercial” does not automatically mean inexperienced: classifications, reporting thresholds, and contract structure must be understood before deriving a signal.
Seasonality looks for recurrences associated with the calendar. A historical average may describe context, but loses meaning when the window is selected after seeing the result, the sample is small, or market regimes and costs have changed.
Testable rules
Williams's books organize ideas about volatility, short-term patterns, exits, and position management. The transferable contribution is the move from an intuition to an observable rule: market, time window, condition, invalidation, and risk should be stated before testing. The books collect different techniques; they do not constitute one universal system.
Limits and attribution
The author's website is a primary source for what Williams says he developed, but it is not independent verification. The contest archive also belongs to the organizer. Publisher records confirm titles and subject matter, not the future profitability of a strategy.
Williams %R depends on the chosen lookback; COT data are aggregated and delayed; seasonality is vulnerable to selecting only patterns that survived historical screening. None of these replaces position sizing, costs, liquidity, or drawdown control.
What to study today
To understand %R, first observe the high, low, and close over a fixed window without immediately searching for signals. Then compare the same rule in trending and ranging conditions. For COT and calendar data, record when the observation was actually available and prevent the test from using future information. A credible backtest separates rule definition from evaluation and includes costs and adverse cases.
The useful outcome is not to imitate the 1987 contest, but to answer four questions: what does the rule measure, when was the input knowable, how much risk does it take, and under which conditions does it stop working?
Sources
- World Cup Trading Championships — Historical Standings
- Larry Williams — Original Williams %R
- U.S. CFTC — Commitments of Traders, Explanatory Notes
- Wiley — Long-Term Secrets to Short-Term Trading
Related entries
Williams %R · Stochastic · COT report · Market seasonality · Backtest · Position sizing · Traders and traditions